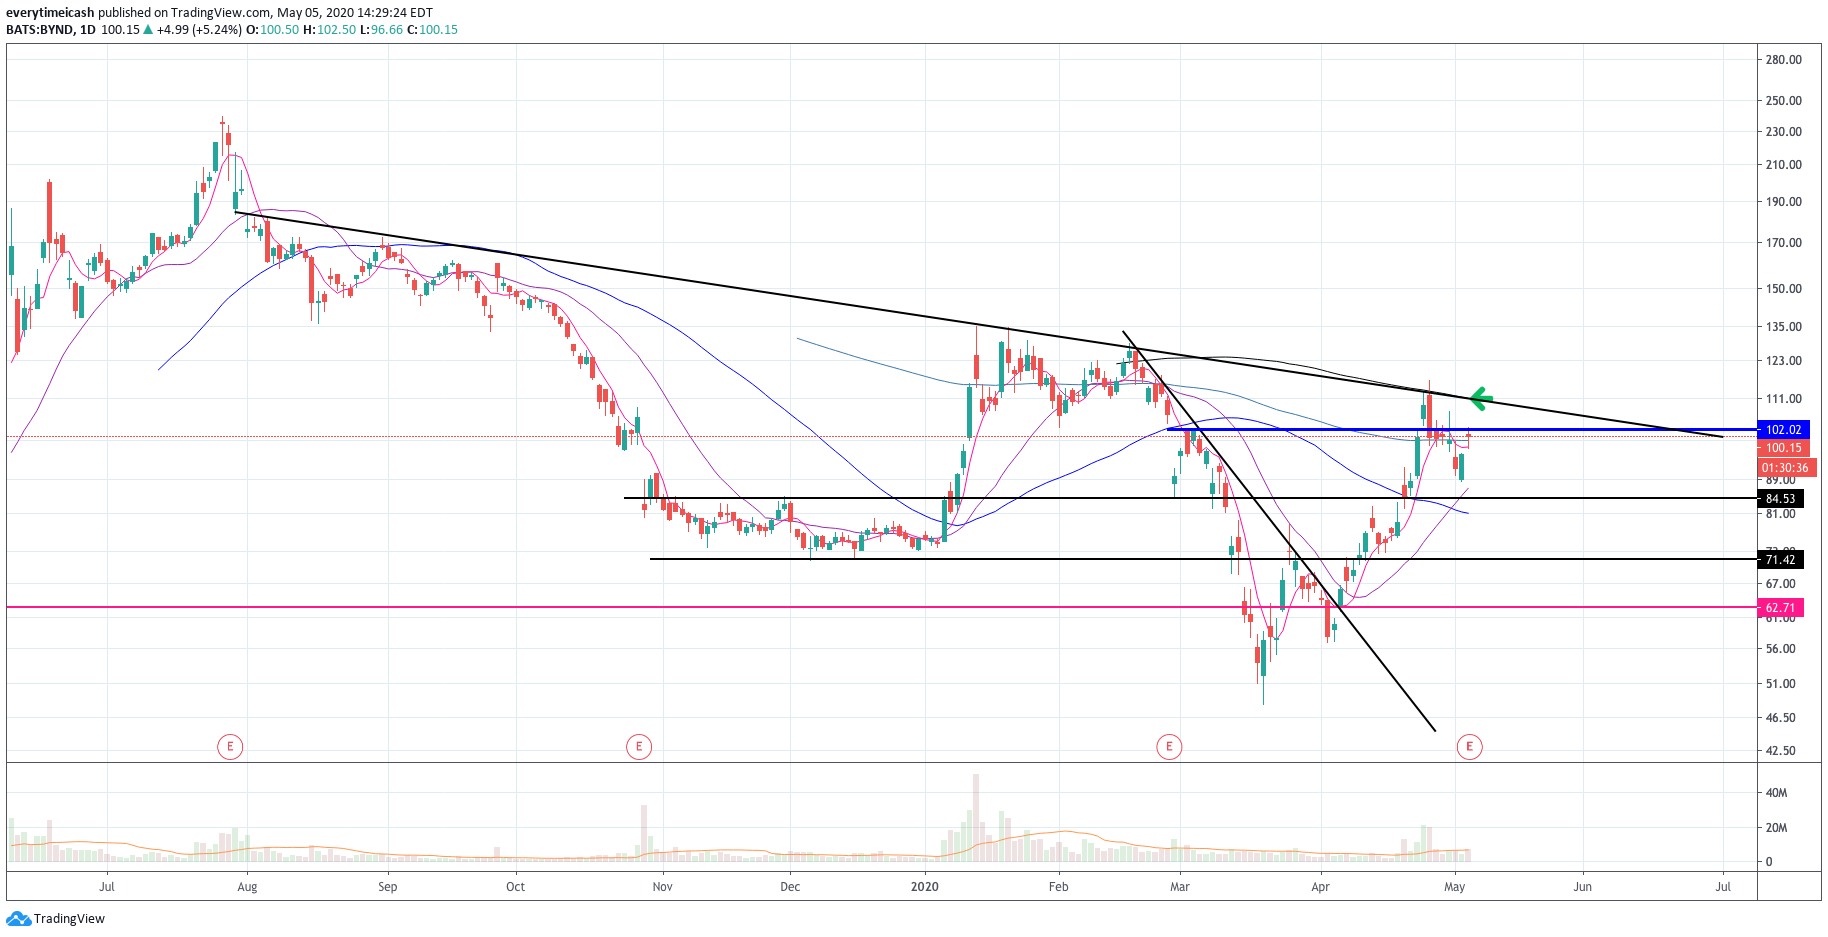
Beyond Meat (BYND) is set to report Q1 results today after the close with a call to follow at 4:30pm ET.
Current consensus is for EPS of $(0.08) and revenue of $87.1 mln. BYND typically guides for 2020 revenue, but that may change with the pandemic. Adjusted EBITDA is a metric to watch with BYND.
Last quarter, BYND reported a penny EPS miss despite revenue jumping 213% yr/yr to $98.5 mln, well above the $81.5 mln consensus. This tells us that margins were lower than expected.
BYND can be pretty hit or miss around earnings. In the four quarters since its IPO in mid-2019, BYND has missed on EPS consensus twice and has beaten twice. The fact that BYND does not guide on a quarterly basis may partly explain the volatility.
Hopefully, we get some color from BYND on some headwinds it's facing
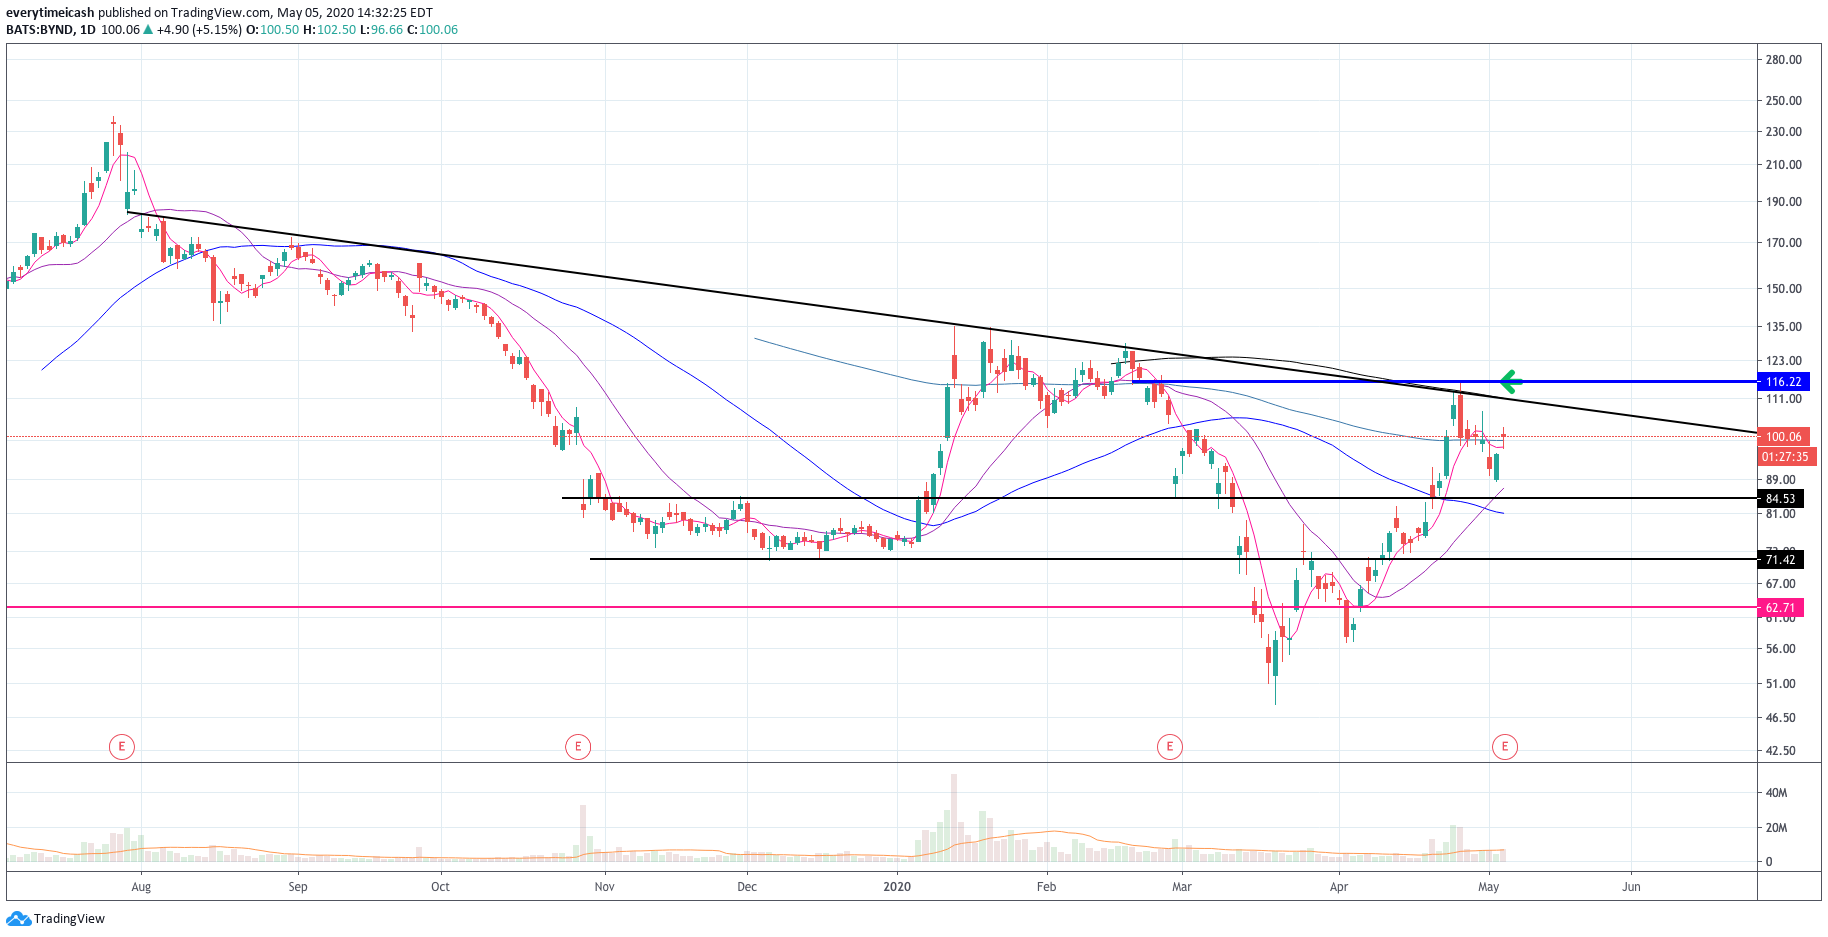
RESULTS:
Beyond Meat beats by $0.11, beats on revs, suspends 2020 outlook
Analysts were expecting a Q1 loss but BYND surprised with a $0.03 profit. Revenue jumped 141.5% yr/yr to $97.1 mln, also much better than expected. With stocks hovering around breakeven, we think it's useful to track adjusted EBITDA. That jumped to $12.7 mln from a $(2.1) mln loss last year.
Margins are important because the 2020 EBITDA margin guidance was a big reason the stock fell sharply on last quarter's results.
In February, BYND said it expects 2020 adjusted EBITDA margin to be flat with 2019's 8.5% result.
Typically, as revenue rises (and +141% growth in Q1 shows sales are booming), investors expect margins to also rise as the company benefits from economies of scale. To see flat margins was disappointing.
BYND explained by saying it was accelerating investments in marketing, R&D, and international expansion in 2020.
BYND posted 13.1% adjusted EBITDA margins in Q1. So, the company is already tracking well above the 8.5% full year guidance.
BYND has started to break out sales by channel: Retail (grocery stores, mass retailers, Costco) and Foodservice (restaurants, schools) and by region: US/International. The channel breakdown will be especially helpful to our analysis over the coming quarters as COVID makes its impact.
Foodservice is expected to be hurt as restaurants close or are limited to takeout. Retail could have crosswinds; it should benefit from a possible meat shortage at grocery chains but BYND's premium pricing might make consumers pause in a tough economy. It will be interesting to see how this plays out and the sales breakdown will help a lot with our analysis.
In the US, Retail dwarfs Foodservice at 69%/31% of US sales. However, this relationship is flipped internationally as Foodservice dominates Retail 76%/24%. Our initial thought on why this is important for BYND is because BYND's fairly small Retail segment in the US may help it weather the restaurant closures better than we thought.
BYND's operating leverage is flexing its muscles as sales are getting substantial. The company is growing from a niche product to a mainstream one and that's propelling BYND into profitability. The other key thing here is margins. BYND's adjusted EBITDA margin came in well ahead of guidance. This is easing investors' concerns about margin compression in 2020. The margin compression may not be as bad as BYND said it will be.
If you liked this content please click the ❤️ below and/or share this post.
TOTALLY FREE Trading Packet!
Click here to get my packet that shows you how I traded $600 into $100K FOR FREE.
This packet will explain to you in depth how I trade and how I manage my risk.
I am happy to share this. Just use the code KPAKFRAUD at checkout and you will get it TOTALLY FREE. You will pay absolutely nothing.
SHAMLESS PLUGS
CLICK HERE TO CHECK OUT MY 2020 PREVIEW OPINION PACKET. OVER 140 PAGES OF CONTENT AND INFORMATION AVAILABLE HERE.
Check out the latest episodes on my YouTube and SoundCloud channels below.